Week 6 - Multivariate Newton Rhapson Solver
AIM: To write a python program to solve the given system of equations using Multivariate Newton solver.
- Equations
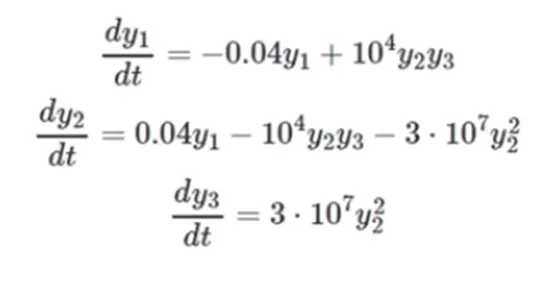
INTRODUCTION
Life is nonlinear, and its many diverse occurrences are frequently related to one another. Because each equation depends on the variables that have been solved for in the other equations, the dynamic evolution of a system or a material cannot be described by the independent solutions of a material balance, a momentum balance, and an energy balance. Thus, systems of nonlinear equations are created to describe intriguing events. Nowadays, trustworthy tools are available to methodically solve systems of nonlinear algebraic equations, just as it was the case when solving a single nonlinear algebraic problem. Finding a decent first guess is difficult when solving a single nonlinear algebraic equation. You may imagine that wandering in n-dimensional space in search of an n-dimensional starting point is substantially more challenging if you think that searching in one-dimensional space for an initial guess that will allow the procedure to converge is uncomfortable. However, it is possible. It is necessary to have access to the proper numerical tool in addition to the knowledge of the physical system. Thus, in this work we will focus on the utilization of multivariate Newton-Raphson method to solve the system of non-linear equations shown above. For this, a Python program will be written to show all steps involved as well as the solution.
THEORY
Multivariate Newton-Raphson Method
Not surprisingly, the Multivariate Newton-Raphson method is a direct extension of the single variable Newton-Raphson method. Where the single variable Newton-Raphson method solved f (x) = 0, the multivariate version will solve a system of n equations of the form
`f_1 (x_1,x_2,x_3,…x_(n-1),x_n )=0`
`f_2 (x_1,x_2,x_3,…x_(n-1),x_n )=0`
`f_3 (x_1,x_2,x_3,…x_(n-1),x_n )=0`
.............
............. (1)
.............
`f_(n-1) (x_1,x_2,x_3,…x_(n-1),x_n )=0`
`f_n (x_1,x_2,x_3,…x_(n-1),x_n )=0`
We will adopt the short-hand notation for the
`ul f(ul x)=0` (2)
Note that this short hand notation does not here imply anything about the linearity of any of the equations in `ul f(ul x)` . The basis of the single variable Newton-Raphson method lay in the fact that we approximate the derivative of f (x) numerically using a forward finite difference formula based on a truncated Taylor series,
`f^' (x_1 )=df/dx |_(x_1 )≈(f(x_1 )-f(x_2 ))/(x_1-x_2 )` (3)
Multivariate Taylor series also exist. The idea behind the multivariate Taylor series lies in the definition of the total derivate of a multivariate function. For a function of two variable we can write,
`df(x_1,x_2 )=(∂f/(∂x_1 ))_(x_2 ) dx_1+(∂f/(∂x_2 ))_(x_1 )dx_2` (4)
Where `((∂f)/(∂x_2 ))_(x_1 )` is called the partial derivative of the function f with respect to variable x1. The subscript outside the parentheses in a partial derivative indicates variables that were treated as constants during the differentiation. For a function of n variables, we have
`df(▁x)= ∑_(i=1)^n((∂f)/(∂x_i ))_(x_m≠i) dx_i` (5)
The multivariate Taylor series expansion, truncated after the first derivative is thus
`f(▁x^((k) ) )-f(▁x^((k+1) ) )=∑_(i=1)^n(∂f/(∂x_i ))_(x_m≠i) |_(▁x^((k) ) ) (x_i^((k) )-x_i^((k+1) ) )` (6)
Let it be clear that the i subscript on the variable x indicates a different independent variable. The superscript (k) on the x is not an exponent. The parentheses are included to make clear it is a notation that does not signify a mathematical operation. Instead, the superscript (k) indicates a different value of x, which we shall soon see can be associated with the k and k+1 iterations of the Newton-Raphson method. The subscript that now appears outside the parentheses, `x_m≠i` , indicates that all variables except `x_m` are held constant in the differentiation. The final subscript `ulx^((k) )` of the partial derivative indicates the value of `ulx` where the derivative is evaluated.
If n=1, then equation (6) simplifies to
`f(x_1^((k) ) )-f(x_1^((k+1) ) )=(df)/(dx_1 ) |_(▁x^((k) ) ) (x_i^((k) )-x_i^((k+1) ) )` (7)
The equation (7) can be rearranged for `x_1^((k+1) )`
`x_1^((k+1) )=x_1^((k) )-(f(x_1^((k) ) )-f(x_1^((k+1) ) ))/((df)/(dx_1 ) |_(▁x^((k) ) ) )` (8)
which is precisely the Newton-Raphson method once we set `f(x_1^((k+1) ) )=0` . Similarly for the multivariate case, in which we have n equation and n unknowns, we write equation (6) for every function.
`f_j (ulx^((k) ) )-f_j (ulx^((k+1) ) )=∑_(i=1)^n((∂f)/(∂x_i ))_(x_m≠i) |_(▁x^((k) ) ) (x_i^((k) )-x_i^((k+1) ) )` (9)
where all that has been done is to add a subscript j to f., identifying each equation from j = 1 to n. Equation (9) is a system of nonlinear algebraic equations. The n unknowns are the next iteration of x, `x_1^((k+1) )` . Following the Newton-Raphson procedure, we set f j(`x^((k+1) )`)= 0 for all j. Again, this choice is based on the fact that we intend for our next estimate to be a better approximation of the root, at which the functions are zero. By convention, we express equation (9) in matrix notation as
`ul ul(J)^((k) ) ▁delta^((k) )=-ulR^((k) )` (10)
where `ul R^((k) )` is called the residual vector at the kth iteration and defined as
`ulR^((k) ) ≡ulf (ulx^((k) ) )` (11)
In other words, the residual is simply a vector of the values of the functions evaluated at the
current guess. The Jacobian matrix at the kth iteration,`ul ul(J)^((k) )` , defined as
`J_(j,i)^((k) )≡((∂f_j)/(∂x_i ))_(x_m≠i) |_(▁x^((k) ) )` (12)
Thus, the Jacobian matrix is an nxn matrix of all the possible pairwise combinations of partial first derivatives between n unknown variables, `x_i`, and n functions, `f_j`. The difference vector,`ul deltax^((k) )` , is defined as
`uldeltax^((k) )≡ulx^((k+1) )-ulx^((k) )` (13)
The difference vector can be rearranged for the value of x at the new iteration,
`ulx^((k+1) )≡ulx^((k) )+uldeltax^((k) )` (14)
The algorithm for solving a system of nonlinear algebraic equations via the multivariate Newton-Raphson method follows analogously from the single variable version. The steps are as follows:
- Make an initial guess for `ulx`.
- Calculate the Jacobian and the Residual at the current value of `ulx`.
- Solve equation (10) for `uldeltax^((k) )`.
- Calculate `ulx^((k+1) )` from equation (14).
- If the solution has not converged, loop back to step 2.
The multivariate Newton-Raphson Method suffers from the same short-comings as the single variable Newton-Raphson Method. Specifically, as with all methods for solving nonlinear algebraic equations, you need a good initial guess. Second, the method does provide fast (quadratic) convergence until you are close to the solution. Third, if the determinant of the Jacobian is zero, the method fails. This last constraint is the multi-dimensional analogue of the fact that the single variable Newton-Raphson method diverged when the derivative was zero.
The determination of convergence of a system that has multiple variables requires a tolerance. One could use a tolerance on each variable. That is the relative error on `x_i` must be less than `Tol_i`. Alternatively, one can use something like the root mean square (RMS) error,
`err_(RMS)^((k) )=√(1/n ∑_(i=1)^n((x_i^((k) )-x_i^((k-1) ))/x_i^((k-1) ) )^2 )`
to provide a single error for the entire system. In this case, even with an RMS relative error on x of 10^(-m), you are not guaranteed that every variable has m good significant digits. You are only guaranteed that the RMS error is less than the acceptable tolerance.
Procedure followed to solve the given system of equations
- The given initial conditions for the three variables are:
`y_1 [0]=1`
`y_2 [0]=0`
`y_3 [0]=0`
- The actual equations look like when the differentiation applied
`(y_1^n-y_1^(n-1))/(∆t)=-0.04y_1^n+ 10^4 y_2^n y_3^n`
`(y_2^n-y_2^(n-1))/(∆t)=0.04y_1^n-10^4 y_2^n y_3^n-3.10^7 (y_2^n )^2`
`(y_3^n-y_3^(n-1))/(∆t)=3.10^7 (y_2^n )^2`
- The actual process of multivariate Newton Raphson method is finding the roots of zeros.
- Now, we need to rearrange the above equations to a system of root finding functions
- Applying the Backward differencing method for ODE’s.
`f_1^n=y_1^n+∆t(0.04y_1^n- 10^4 y_2^n y_3^n )-y_1^(n-1)=0`
`f_2^n=y_2^n-∆t(0.04y_1^n-10^4 y_2^n y_3^n-3.10^7 (y_2^n )^2 )-y_2^(n-1)=0`
`f_3^n=y_3^n-∆t(3.10^7 (y_2^n )^2 )-y_3^(n-1)=0`
Where,
- After setting up the equations for all the three functions, now we need to find the Jacobian matrix using these matrices
`J=[[(∂f_1^n)/(∂y_1^n ),(∂f_1^n)/(∂y_2^n ),(∂f_1^n)/(∂y_3^n )],[(∂f_2^n)/(∂y_1^n ),(∂f_2^n)/(∂y_2^n ),(∂f_2^n)/(∂y_3^n )],[(∂f_3^n)/(∂y_1^n ),(∂f_3^n)/(∂y_2^n ),(∂f_3^n)/(∂y_3^n )]]`
- The final equation or the general equation for the multivariate Newton Raphson method is written as:
`y_(i+1)^n=y_i^n-α.[J^(-1) ].F^n` where F is a functional or final matrix y_i+1 is the new valued matrix and y_i is the old valued matrix. In this case, we have:
`F=[[f_1],[f_2],[f_3 ]]`
And i+1 represents the new iteration, I is for the old or previous iteration and α is the relaxation factor.
Program
"""
This python program is written to solve a system of coupled non-linear equations
using multivariate Newton-Raphson solver

dy1/dt = -0.04*y1 + 10^4*y2*y3
dy2/dt = 0.04*y1 - 10^4y2*y3 - 3.10^7*y2^2
dy3/dt = 3.10^7*y2^2

"""

import matplotlib.pyplot as plt
import numpy as np
from numpy.linalg import inv

#Time interval definition

t_start = 0
t_end = 600
dt = 0.01
n = int((t_end-t_start)/dt)


def f1(y1_old, y1, y2, y3, dt):

	# First non-linear equation
	return y1_old + dt*(-0.04*y1 + 1*10**4*y2*y3) - y1


def f2(y2_old, y1, y2, y3, dt):
	#Second non-linear equation

	return y2_old + dt*(0.04*y1 - 10**4*y2*y3 - 3*10**7*y2**2) - y2

def f3(y3_old, y1, y2, y3, dt):

	# Third non-linear equation

	return y3_old + dt*(3*10**7*y2**2) - y3

def Jacobian(y1_old, y2_old, y3_old, y1, y2, y3, dt):
	J = np.ones((3,3))
	h = 1e-5
	# Row 1
	J[0,0] = (f1(y1_old, y1+h, y2, y3, dt) - f1(y1_old, y1, y2, y3, dt))/h
	J[0,1] = (f1(y1_old, y1, y2+h, y3, dt) - f1(y1_old, y1, y2, y3, dt))/h
	J[0,2] = (f1(y1_old, y1+h, y2, y3+h, dt) - f1(y1_old, y1, y2, y3, dt))/h

	# Row 2
	J[1,0] = (f2(y2_old, y1+h, y2, y3, dt) - f2(y2_old, y1, y2, y3, dt))/h;
	J[1,1] = (f2(y2_old, y1, y2+h, y3, dt) - f2(y2_old, y1, y2, y3, dt))/h;
	J[1,2] = (f2(y2_old, y1, y2, y3+h, dt) - f2(y2_old, y1, y2, y3, dt))/h;

	# Row 3
	J[2,0] = (f3(y3_old, y1+h, y2, y3, dt) - f3(y3_old, y1, y2, y3, dt))/h;
	J[2,1] = (f3(y3_old, y1, y2+h, y3, dt) - f3(y3_old, y1, y2, y3, dt))/h;
	J[2,2] = (f3(y3_old, y1, y2, y3+h, dt) - f3(y3_old, y1, y2, y3, dt))/h;

	return J


#Initial guess values definition

y1_old = 1
y2_old = 0
y3_old = 0


#Defining the column vector

Y_old = np.ones((3,1))
Y_old[0] = y1_old
Y_old[1] = y2_old
Y_old[2] = y3_old
#Defining the guess values column vector


F = np.copy(Y_old)

#Defining the initial error
error = 9e9

alpha = 1

tol = 1e-6

y_1 = []
y_2 = []
y_3 = []

iteration = []


#Time iteration loop

iter = 1

for i in range(0,n):

	# Entering the Newton Raphson loop

	while error > tol:


		#Computing the numerical Jacobian- old values are used
		J = Jacobian(y1_old, y2_old, y3_old,Y_old[0], Y_old[1], Y_old[2], dt)

		#Computing the F vector
		F[0] = f1(y1_old, Y_old[0], Y_old[1], Y_old[2], dt)
		F[1] = f2(y2_old, Y_old[0], Y_old[1], Y_old[2], dt)
		F[2] = f3(y3_old, Y_old[0], Y_old[1], Y_old[2], dt)


		#Computing the new values

		Y_new = Y_old - alpha*np.matmul(inv(J),F)

		#Computing the maximum absolute error

		error = np.max(np.abs(Y_new - Y_old))

		#Updating old values

		Y_old = Y_new;

	#log message

	log_message = 'iteration # = {0} y1={1} y2= {2} y3={3}' .format(iter, Y_new[0], Y_new[1], Y_new[2])

	print(log_message)

	iter = iter + 1

	#Final results

	y_1.append(Y_new[0])
	y_2.append(Y_new[1])
	y_3.append(Y_new[2])

	iteration.append(iter)

	Y_old = Y_new

	y1_old = Y_new[0]
	y2_old = Y_new[1]
	y3_old = Y_new[2]
	error = 9e9


plt.plot(iteration,y_1,color='black')
plt.plot(iteration,y_2,color='orange')
plt.plot(iteration,y_3,color='blue')
plt.legend(['y_1','y_2','y_3'])
plt.xlabel('Number of steps')
plt.ylabel('Variables')
plt.title('Multivariate Newton Raphson Method For dt = 0.01')
plt.show()
Stepwise explanation of the code
- At the beginning of the program, the relevant libraries are imported which are “matplotlib.pyplot”, “numpy” and “inv”. The first module allows us to plot the results. The second one allows us to perform mathematical operation and use different functions. The third module allows us to take the inverse of a matrix.
- The time step as well as the number of grids are defined
- Now, three functions (f1, f2 and f3) are defined; each of them representing the one of the three non-linear equations
- The Jacobian function is defined allowing us to compute the Jacobian matrix elements.
- The initial guess values for y1, y2 and y3 are defined
- The column vectors are defined and the F matrix is also defined
- The initial value of error, and alpha as well as tolerance values are defined
- The time loop is entered using a “for loop” which runs for n iterations where n is the number of grid points
- The Newton Raphson loop is then entered using a “while loop” which is exited once the error is less than the tolerance value
- The numerical Jacobian and F vector are computed within the previous loops.
- The new values are then computed using the general formula shown above
- The results are stored in three empty arrays y_1, y_2 and y_3.
- Finally, the obtained results are plotted using “plot” command.
Output
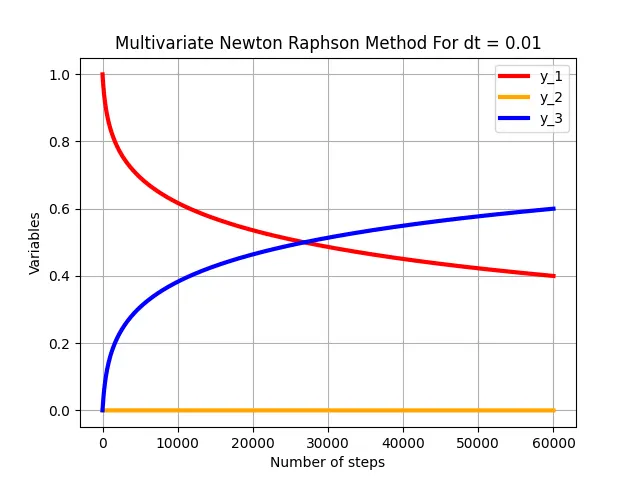
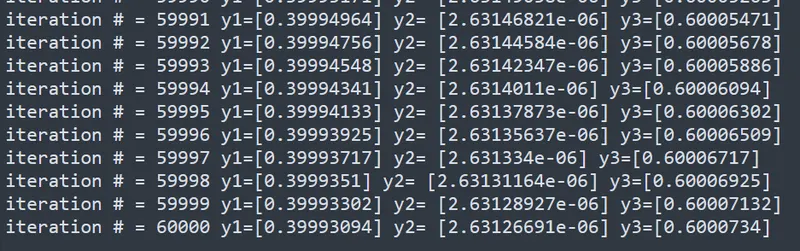
- Case 1 (dt = 0.01)
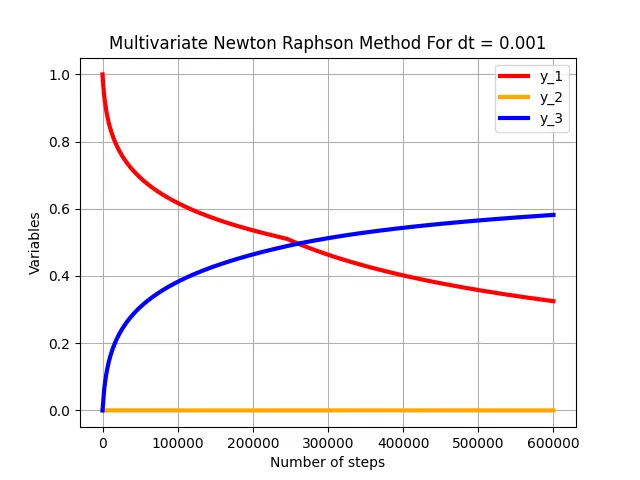
- Case 2 (dt = 0.001)
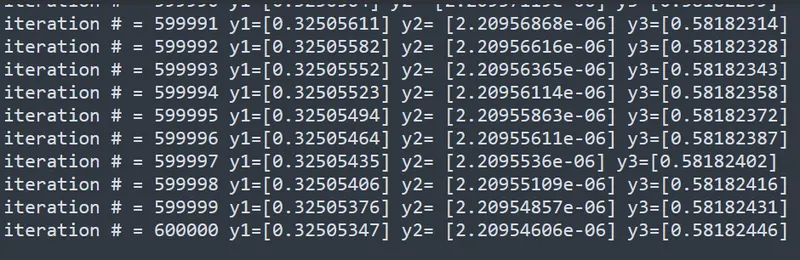
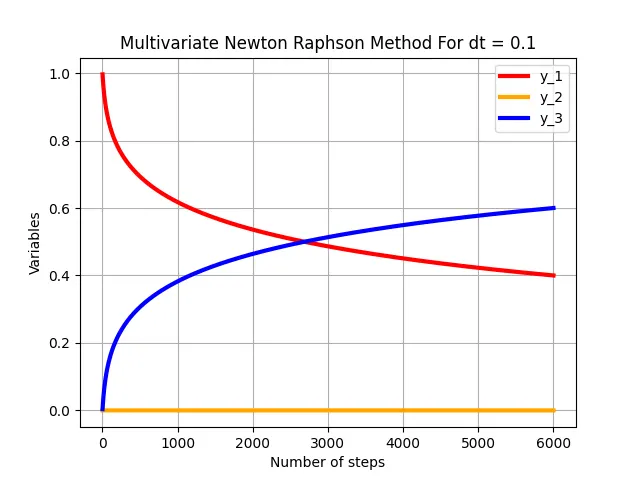
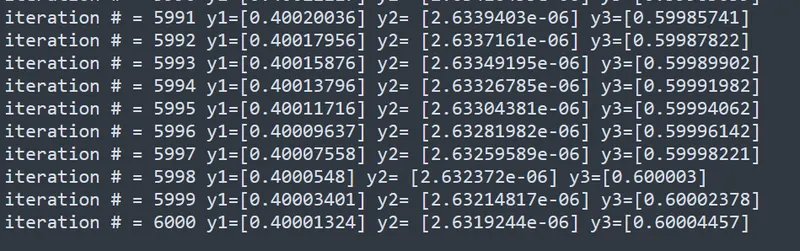
- Case 3 (dt = 0.1)
Selecting an appropriate time step size:
Prior to running the code and obtaining a solution, the time step dt is first set to 0.01. Run the simulation a second time with the time step value set to 0.001. However, the plot and solution are identical. The simulation was ran a third time with the time step aggressively raised to dt =0.1. But nothing has changed as of yet. The length of the simulation also didn't vary significantly. This means that the change in time step does not affect the solution, which is stable and finally converges to produce findings that are fully meaningful. Therefore, the simulation is unaffected by the time step size. Since we are employing the implicit technique as an iterative solver and it is unaffected by the time step size, the simulation is absolutely stable.
In fact, if we utilize an explicit method as the iterative solver, the change in time step size can have an impact on the solution. Despite being relatively challenging to implement, implicit techniques can perform incredibly well in complex scenarios like the stiffness of non-linear coupled equations, rapid increases in temperature, pressure, and mass flow rate, etc. These situations can also occur when the implicit schemes are not easily codable.
Conclusion
The apex values of y1, y2, and y3 are changing fast with regard to the time in the X-axis, as seen by the aforementioned graphs. As the solution advances in time, these variables are changing quickly. Due to the stiff nature of the equation system, this nature is observed.