CFD: From Math to Magic
The size of a matrix (which is known as the order of the matrix) is determined by the number of rows and columns in the matrix.
 Navin Baskar·23 Jun 2023·7 min read
CFD: From Math to Magic
What are Matrices?
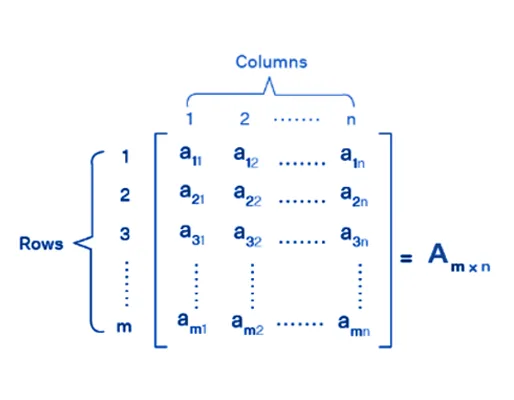
Matrices, the plural form of a matrix, are the arrangements of numbers, variables, symbols, or expressions in a rectangular table that contains various numbers of rows and columns. They are rectangular-shaped arrays, for which different operations like addition, multiplication, and transposition are defined. The numbers or entries in the matrix are known as its elements. Horizontal entries of matrices are called rows and vertical entries are known as columns.
The size of a matrix (which is known as the order of the matrix) is determined by the number of rows and columns in the matrix. The order of a matrix with 6 rows and 4 columns is represented as a 6 × 4 and is read as 6 by 4. For example, the given matrix A is a 2 × 4 matrix and is written as A2 x 4.
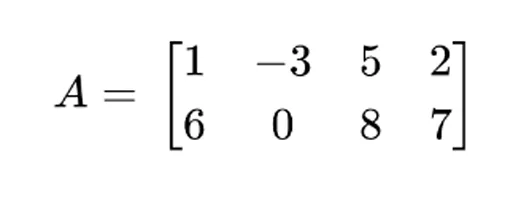
In general the matrix is represented by.
Multiplication of Matrices
Matrices multiplication is defined only if the number of columns in the first matrix and rows in the second matrix are equal. To understand how matrices are multiplied
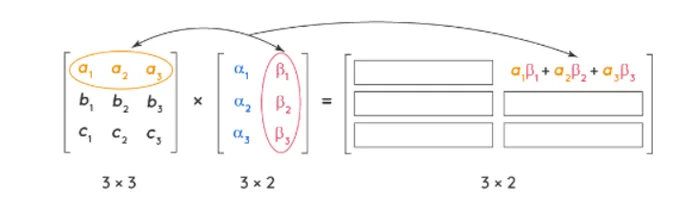
Let A be of order m × n and B be of order n × p. The matrix AB will be of order m × p and will be obtained by multiplying each row vector of A successively with column vectors in B. Let us understand this using a example:
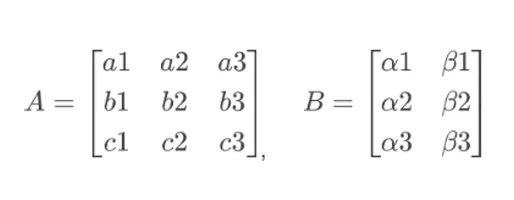
To obtain the element a11of AB, we multiply R1of A with C1of B:
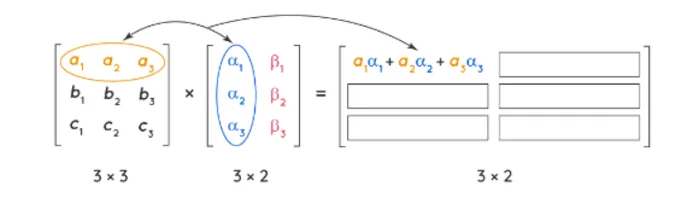
To obtain the element a12of AB, we multiply R1of A with C2of B:
To obtain the element a21of AB, we multiply R2of A with C1of B:
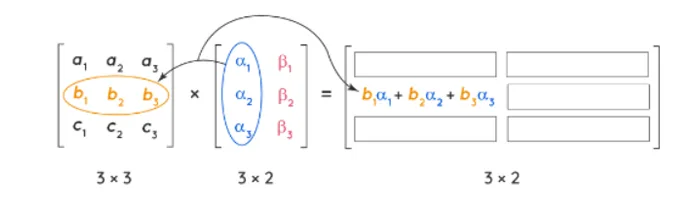
Proceeding this way, we obtain all the elements of AB.
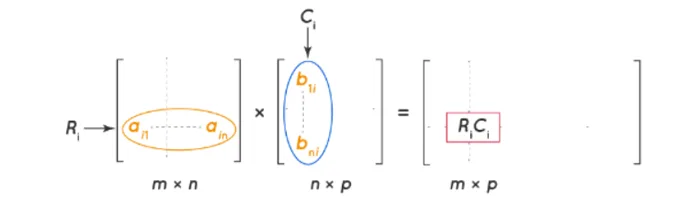
Let us generalize this: if A is or order m × n, and B of order n × p, then to obtain the element aijof AB, we multiply Riof A with Cjof B
Properties of Matrix Multiplication
There are different properties associated with the multiplication of matrices. For any three matrices A, B, and C:
- AB ≠ BA
- A(BC) = (AB)C
- A(B + C) = AB + AC
- (A + B)C = AC + BC
- AIm=A=AIn ,for identity matrices Imand In
- Am x nOn x p=Om x p,where O is a null matrix.
Inverse Matrices
DEFINITION The matrix A is invertible if there exists a matrix A-1 such that
A-1A = I and AA-1 = I
Suppose A is a square matrix. We look for an “inverse matrix” A-1 of the same size, such that A-1 times A equals I . Whatever A does, A-1 undoes. Their product is the identity matrix—which does nothing to a vector, so A-1Ax = x. But A1 might not exist.
What a matrix mostly does is to multiply a vector x. Multiplying Ax = b by A-1 gives
A-1Ax = A-1b. This is x = A-1b. The product A-1A is like multiplying by a number and then dividing by that number. A number has an inverse if it is not zero— matrices are more complicated and more interesting. The matrix A-1 is called “A inverse.”
Not all matrices have inverses. This is the first question we ask about a square matrix: Is A invertible? We don’t mean that we immediately calculate A-1. In most problems we never compute it! Here are six “notes” about A-1.
Method 1 : One of the most important methods of finding the matrix inverse involves finding the minors and cofactors of elements of the given matrix. Observe the below steps to understand this method clearly.
- The inverse matrix is also found using the following equation:
A-1= adj(A)/det(A),
where adj(A) refers to the adjoint of a matrix A, det(A) refers to the determinant of a matrix A.
- The adjoint of a matrix A or adj(A) can be found using the following method.
In order to find the adjoint of a matrix A first, find the cofactor matrix of a given matrix and then take the transpose of a cofactor matrix.
- The cofactor of a matrix can be obtained as
Cij = (-1)i+j det (Mij)
Here, Mij refers to the (i,j)th minor matrix after removing the ith row and the jth column. You can also say that the transpose of a cofactor matrix is also called the adjoint of a matrix A.
Method 2 : Let us consider three matrices X, A and B such that X = AB. To determine the inverse of a matrix using elementary transformation, we convert the given matrix into an identity matrix. If the inverse of matrix A, A-1 exists then to determine A-1 using elementary row operations
- Write A = IA, where I is the identity matrix of the same order as A.
- Apply a sequence of row operations till we get an identity matrix on the LHS and use the same elementary operations on the RHS to get I = BA. The matrix B on the RHS is the inverse of matrix A.
- To find the inverse of A using column operations, write A = IA and apply column operations sequentially till I = AB is obtained, where B is the inverse matrix of A.
Eigenvalue
Eigenvalues are the special set of scalars associated with the system of linear equations. It is mostly used in matrix equations. ‘Eigen’ is a German word that means ‘proper’ or ‘characteristic’. Therefore, the term eigenvalue can be termed as characteristic value, characteristic root, proper values or latent roots as well. In simple words, the eigenvalue is a scalar that is used to transform the eigenvector. The basic equation is
Ax = λx
The number or scalar value “λ” is an eigenvalue of A.
In Mathematics, an eigenvector corresponds to the real non zero eigenvalues which point in the direction stretched by the transformation whereas eigenvalue is considered as a factor by which it is stretched. In case, if the eigenvalue is negative, the direction of the transformation is negative.
For every real matrix, there is an eigenvalue. Sometimes it might be complex. The existence of the eigenvalue for the complex matrices is equal to the fundamental theorem of algebra.
Eigenvalues of a Square Matrix
Suppose, An×n is a square matrix, then [A- λI] is called an Eigen or characteristic matrix, which is an indefinite or undefined scalar. Where determinant of Eigen matrix can be written as, |A- λI| and |A- λI| = 0 is the Eigen equation or characteristics equation, where “I” is the identity matrix. The roots of an Eigen matrix are called Eigen roots.
Eigenvalues of a triangular matrix and diagonal matrix are equivalent to the elements on the principal diagonals. But eigenvalues of the scalar matrix are the scalar only.
Properties of Eigenvalues
- Eigenvectors with Distinct Eigenvalues are Linearly Independent
- Singular Matrices have Zero Eigenvalues
- If A is a square matrix, then λ = 0 is not an eigenvalue of A
- For a scalar multiple of a matrix: If A is a square matrix and λ is an eigenvalue of A. Then, aλ is an eigenvalue of aA.
- For Matrix powers: If A is square matrix and λ is an eigenvalue of A and n≥0 is an integer, then λn is an eigenvalue of An.
- For polynomials of matrix: If A is a square matrix, λ is an eigenvalue of A and p(x) is a polynomial in variable x, then p(λ) is the eigenvalue of matrix p(A).
- Inverse Matrix: If A is a square matrix, λ is an eigenvalue of A, then λ-1 is an eigenvalue of A-1
- Transpose matrix: If A is a square matrix, λ is an eigenvalue of A, then λ is an eigenvalue of At
EigenVectors
Eigenvectors are the vectors (non-zero) that do not change the direction when any linear transformation is applied. It changes by only a scalar factor. In a brief, we can say, if A is a linear transformation from a vector space V and x is a vector in V, which is not a zero vector, then v is an eigenvector of A if A(X) is a scalar multiple of x.
An Eigenspace of vector x consists of a set of all eigenvectors with the equivalent eigenvalue collectively with the zero vector. Though, the zero vector is not an eigenvector.
Let us say A is an “n × n” matrix and λ is an eigenvalue of matrix A, then x, a non-zero vector, is called as eigenvector if it satisfies the given below expression;
Ax = λx
x is an eigenvector of A corresponding to the eigenvalue, λ.
Note:
- There could be infinitely many Eigenvectors, corresponding to one eigenvalue.
- For distinct eigenvalues, the eigenvectors are linearly dependent.